Tesla’s Profit Slide Persists Despite Margin Recovery in Q3 2026
The electric vehicle maker reported stable revenue but saw operating income drop significantly as spending on artificial intelligence and new vehicles accelerated.
By Leila Saeed ·
Tesla Inc. reported third-quarter results after the market closed on Tuesday, revealing a complex financial picture where revenue remained stable but profitability continued to decline. The company generated $28.05 billion in revenue, a figure that was essentially flat compared to the same period last year and aligned closely with Wall Street expectations. While non-GAAP earnings per share of $0.48 exceeded the consensus estimate of $0.45, the metric still represented a four percent decrease from the $0.50 reported a year ago. On a GAAP basis, net income fell by 43 percent to $787 million, or $0.22 per share, signaling that the underlying earnings pressure has not yet been alleviated.
The core issue remains the company’s inability to convert stable sales into proportional profits. Although automotive gross margin excluding regulatory credits recovered to 18.1 percent, up from 16.3 percent in the previous quarter, operating income plummeted by 56 percent year-over-year to $718 million. This decline was driven by a sharp increase in operating expenses, which rose 39 percent to $4.78 billion. The surge in costs was primarily fueled by aggressive spending on artificial intelligence, the Optimus humanoid robot, and the Cybercab, with research and development expenses jumping 69 percent to $2.76 billion.
Capital expenditures also saw a dramatic shift, with Tesla spending $4.73 billion in the quarter, more than double the $2.25 billion spent in the same period last year. This heavy investment pace has implications for the company’s full-year guidance, which had projected over $25 billion in capital spending for 2026. With only $13.01 billion spent through the first nine months, Tesla would need to double its largest quarterly spending figure in the final quarter to meet that target, a possibility that appears increasingly unlikely given that spending actually decreased sequentially from the second quarter.
In the energy division, revenue fell 16 percent to $2.88 billion, a decline attributed to tariff-related customer refunds despite a 10 percent increase in battery storage deployments. Conversely, the services and other segment emerged as a highlight, with revenue growing 33 percent to $4.61 billion. This growth was driven by record gross profits of $734 million from charging, insurance, and parts sales, providing a buffer against the softer performance in the energy sector.
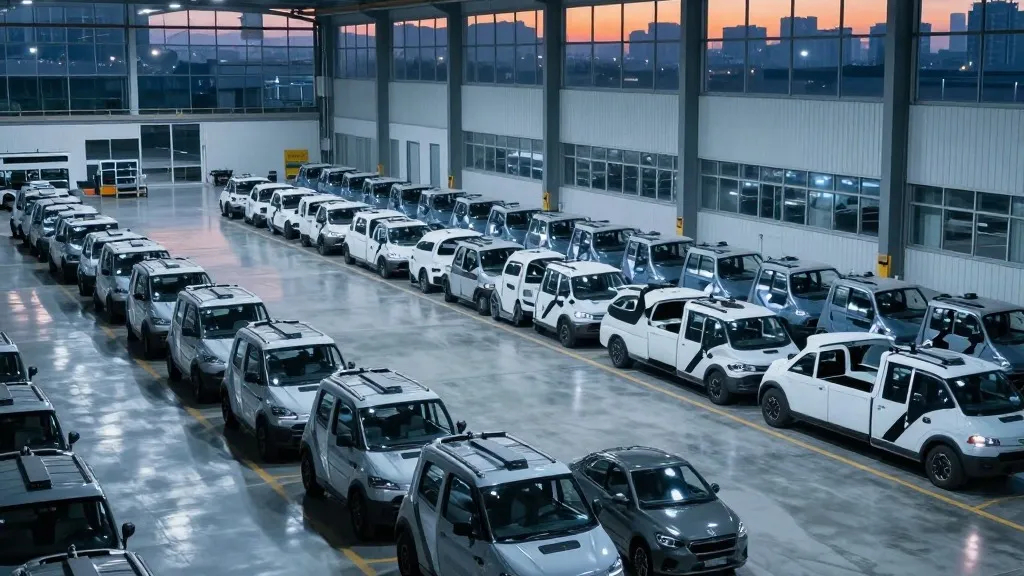
Management attributed the flat vehicle deliveries, which totaled 486,532 units, to a shortage of battery availability rather than a lack of consumer demand. The company stated that it ended the quarter with the largest backlog for passenger vehicles in four years. However, this explanation sits in tension with the fact that average selling prices continued to fall, a strategy typically employed by manufacturers struggling with demand rather than those constrained by supply. Inventory levels did improve, dropping to 11 days of supply from 15 in the second quarter, as deliveries outpaced production.
Autonomy metrics showed progress, with active Full Self-Driving subscriptions reaching 1.74 million, a 67 percent increase year-over-year. The company also noted that its Robotaxi service had accumulated nearly 2 million unsupervised miles by the end of the quarter, a milestone achieved shortly after the Cybercab joined the fleet in Austin. These developments underscore Tesla’s pivot toward software and autonomous driving as key growth drivers, even as traditional automotive margins face pressure.
The company’s balance sheet remains robust, ending the quarter with $45.4 billion in cash and investments. Free cash flow was positive at $1.53 billion, a significant improvement from the negative $1.09 billion recorded in the second quarter, though this figure was bolstered by the lower capital spending pace. Net income also benefited from a $288 million unrealized gain on bitcoin holdings, which was partly offset by a $142 million unrealized loss on its SpaceX equity stake.
Market analysts had entered the reporting period anticipating a flat quarter, with consensus estimates for revenue hovering around $28.06 billion. The actual results matched these expectations, confirming the company’s revenue stability. However, the divergence between the recovery in gross margins and the decline in operating income suggests that Tesla’s strategic investments are still in the heavy spending phase, with profitability gains yet to materialize fully.
Investors will look to management’s commentary during the earnings call for further clarification on the path to profitability. The company’s ability to balance aggressive spending on future technologies with the need to restore operating margins will be critical in determining its financial trajectory heading into the fourth quarter and beyond.
Source: Electrek · original report published
More Business · Business Complaints · Report a business · Got a Story?